Options Trading for Beginners

It does NOT take money to make money. Discover how trading options can provide the financial freedom you desire.

I often hear people say, “It takes money to make money.” This is not true. For Kim and I to go from homeless in 1985 to millionaires in 1989, and then to financial freedom in 1994, it didn’t take money. We had no money when we started, and we were deeply in debt.

It also didn’t take a formal education. I have a degree, and I can tell you that achieving financial freedom had nothing to do with what I learned in college. I didn’t find much demand for my skills in calculus, spherical trigonometry, chemistry, physics, French, and English literature in the real world.

What does it take to get rich?

I’m often asked, “If it doesn’t take money to make money, and schools don’t teach you how to become financially free, then what does it take?”

My answer: It takes a dream, a lot of determination, a willingness to learn quickly, the ability to use your God-given assets properly, and to understand how money works and can work for you.

It starts with financial education

All of the qualities necessary for getting rich, start with financial education—a type of education that you can’t get in a traditional school. My financial education started with my rich dad, my best friend’s dad, and continues today through books, seminars, learned lessons, and mentors. From all these sources, I learned about cash flow, debt, business and investing, taxes, and more—and how to use each to make myself rich.

If you want to be rich, I can’t stress the importance of starting your financial education today. Take some classes, read a book, attend a seminar, and find a great coach. It’s the most important investment you can make.

The most important thing, however, is to believe it’s possible. And believe it’s possible for you. You must change your mindset to a mindset of success rather than a mindset of failure. Most people cannot stop the little voices of doubt and fear that stop them from ever getting started.

So for those people, I would like to address the biggest voice, the voice that says, “How can I invest? I don’t have any money.” The truth is it does not take money to make money. It takes a little imagination and a little guts, but it does not take money.

Instead of telling you my stories again, I’ve asked one of my advisors, Andy Tanner, to share a theoretical story, a parable, followed by an example of putting the lessons from the parable into action.

Options trading example: The parable of the suit

Imagine you knew of a simple process to create money almost out of thin air, and you could follow this process again and again whenever you needed it. Let me walk you through a financial parable to explain how this principle works.

One day, a man walked through his town, peering into the different shop windows along the way. At one particular shop, a beautiful suit caught his eye. So he entered the clothing store and asked the clerk in the store the price of the suit.

“Well,” said the clerk, “this is a very nice suit made of the finest wool. The regular price of this suit is $2,000. Fortunately, today is the final day of a special sale, so the suit is available for just $1,000.” The shopper recognized this as a great value. But, he didn’t have enough money to purchase the suit at that moment.

The man asked, “Is there any other way I can have this suit at this discounted price without paying for it now?” The clerk, wanting to preserve the sale, replied, “I’ll propose a gentleman’s agreement. I will create a layaway plan. We will put the suit on reserve so no one else can get it, as long as you return within 30 days to pay for it in full at the discounted price of $1,000.”

The man felt very good about the agreement proposed by the merchant. He was hopeful that he could come up with the money after paying his expenses that month, but he also felt good that he was not obligated to buy the suit just in case it did not work out.

So the man agreed to put the suit on layaway, and the clerk put it in reserve at the discounted price of $1,000. As proof of this arrangement, the clerk gave the man a slip of paper with the store name, the clerk’s name, the terms of the layaway agreement, and his signature.

Options trading simplified (A Promise and A Choice)
The man could present that slip of paper at any time within thirty days to receive the suit at the sale price. The clerk, acting on behalf of the store, made a promise to sell the suit at a specific price for a certain amount of time. The man had the choice to purchase the suit according to those terms. Even more important, the man has no risk of loss.

The next morning, the man woke up and turned on the news. The main story was about a very popular sports star, and the athlete was wearing the exact same suit that he put on layaway.

Later, the man passed the same shop where he purchased the suit. The store was overflowing with people and there was a line forming just to get in. They were all trying to buy the suit that the athlete was wearing.

Upon hearing this, the man asked a young person in line, “You are willing to buy the suit for the full price of $2,000?” At this, the young man laughed, “I wish I could get it for $2,000. The price went up this morning to $4,000!”

Overnight, the price of the suit doubled based on the new demand for it. The man’s mind started turning. He realized that there was now a line of people who were willing to pay up to $4,000 for this same suit. Yet, in his pocket he had a layaway slip which guaranteed him the right to purchase the suit for just $1,000.

Even more interesting was the fact that those people in line were nervous that the store may sell out of all the suits before they get a chance to buy one. His suit was put away safely in the back of the store where no one else could buy it.

He considered what someone might pay him for his suit that was on layaway. He had two possible ways to take advantage of this situation: He could go into the store, buy the suit for $1,000, and then turn around and sell it to someone else for $4,000. Or, he could just sell his layaway slip for $3,000.

Both scenarios would result in him pocketing $3,000. But the first one would also require that he use $1,000 of his own money to get the suit out of layaway. He realized selling the slip of paper in his pocket for $3,000 was the best choice for him since he didn’t have $1,000 of his own money to start the transaction.

He approached the young man in line again and asked him if he would be interested in making a deal. He explained that he will sell his layaway contract for $3,000, which will entitle him to get the suit for $1,000, and he is guaranteed to get the suit. The young man quickly realized the value of that slip of paper and agreed to buy it. Without spending a penny of his own money, the man made $3,000 in a day.

This is how trading options works.

How to trading options work

Consider if this man was looking to flip a house, buy stock, or buy gold. This is the same scenario that investors exploit every single day. Amateur investors ask amateur questions like these:

“Should I use my own money to buy this house and then hopefully flip it for more?”

“Should I buy 1,000 shares of this stock and hopefully sell it later for more?”

This type of investment profit is called a capital gain. It’s when your ending investment value is worth more than what you paid for the investment. It’s the increase in your investing capital. And it’s the approach which follows the “it takes money to make money” path.

Most people believe that you find a good potential investment, pull money from your bank account to pay for it, and then hope it goes up in value so you can make more money than your initial investment.

However, remember that we didn’t ever buy the suit. All we did was enter into an agreement with someone else. And this agreement cost us no money. The store clerk gave it to us. Instead of requiring money, all we needed was a simple negotiation. The layaway agreement gave us the flexibility to decide if it was valuable enough for us to take action. It didn’t require any money from us—either from our own account or from a loan.

It’s not easy, of course, to always know where the price of something will be next month or next year, but it might be very exciting for you to discover that in real life there are deals you can do that don’t require you to buy anything. Watch Andy’s webinar to learn more about these deals.

Options trading conclusion

The story above is an example of making money with intelligence and imagination. That is not just a story. Whether you realize it or not, opportunities to take very similar actions are presented to you every day. You just don’t see them… yet.

Since birth, and especially since attending school – we have been convinced that it takes money to make money. That is a very dangerous belief. That belief alone will keep most people from ever finding success.

One of the real dangers of that belief is that it makes most people a victim. They believe they do not have a chance since they were never given the same opportunity and tools (money) as others. Once you accept that you are a victim, you will never be in control of your life again. If you are not in control, then you must patiently wait for luck to make you wealthy. Chances are that is a losing strategy. Do not be a victim. Banish this belief from your thoughts.

Another danger of that belief is the pain it causes. If you become a victim, you feel helpless, but you also become angry. Angry at the world for placing you in this unfair situation. Angry at your parents for not being more successful. Look around. Does the world need more angry people? No. Banish this belief. Free your soul of the negative chains that weight you down. Accept responsibility for your own life.

The last point I want to highlight regarding the evil belief that it takes money to make money, is the power it gives you to fail and keep failing. Excuses are dangerous things. And this belief is the mother of all excuses. The power of an excuse is the permission it gives you to never even try.

I don’t care how great your excuse is, it is never going to help you create your success. Have you heard this quote:

“Don’t let life discourage you; everyone who got where he is had to begin where he was.” —Richard Evans

Just let that sink in for a moment. Everyone starts out with challenges, even the most successful people. Overcoming those challenges and reaching one’s goals despite the odds stacked against them, is what propels some people to success. For those who buy into the excuses about why they can’t achieve something, their thoughts become a self-fulfilling prophecy.

CREATE MONEY WITHOUT MONEY

If you’re ready to begin trading options like a pro, take advantage of Andy’s beginning…
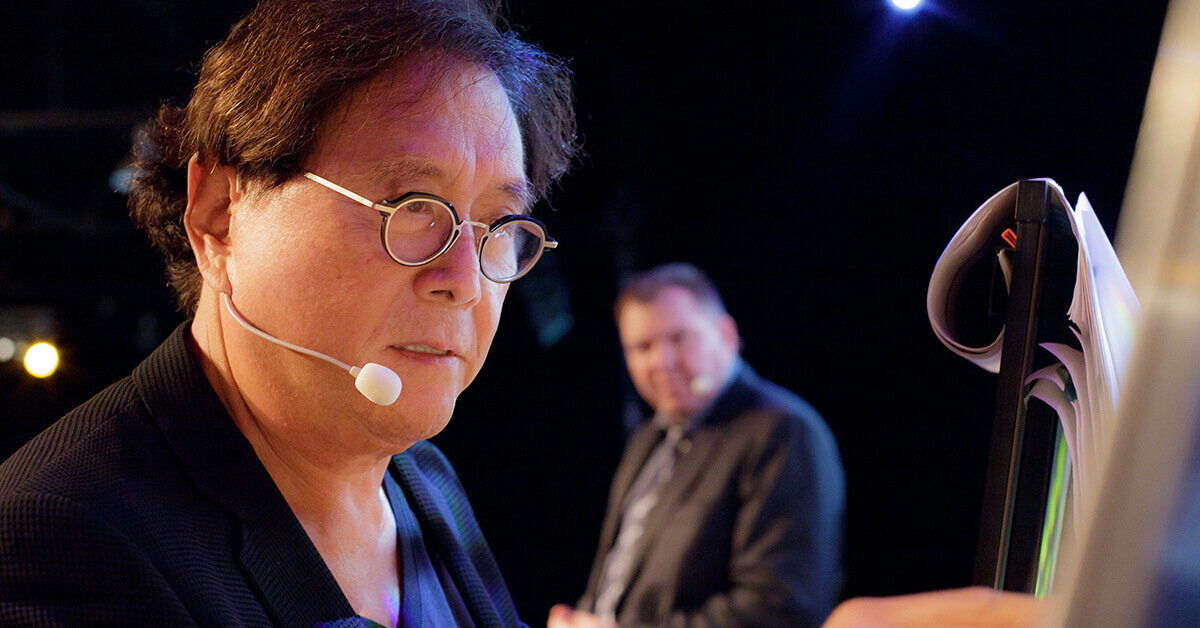
robert kiyosaki and andy tanner on stage

Start Trading Options Here

Change your mind. Change your life. Understand that you can make money without money. Andy showed you how to do it with a suit. He also does the same strategy nearly everyday in the stock market. So if your new excuse was, “I don’t have a tailor shop nearby” or, “I can’t find any deals like that one,” then you are in luck. There are millions of those deals in the stock market every day.

I encourage you to watch this FREE training Andy made for you. Watch this and then see if no money deals are something you’d like to pursue. Because I know you can. http://wordpress.com/refer-a-friend/RNlRO6gsz3AkwOnW0Wo3
How to Know When to Quit a Side Hustle! Turning Your Passion Into Profit

when to quit a side hustle

There is enough for everyone. This is the premise of an abundance mindset, and modern entrepreneurship is perhaps the most tangible example. Digital nomads, full-time freelancers and serial contractors have all seized the countless opportunities to develop a side hustle for extra money, professional growth or even just for kicks. No matter the motivation, there is plenty of pie—somewhere in the billions—to go around. 

Wondering if a side hustle is right for you? Listen to our Hustle From Home podcast to discover proven strategies for turning your passion into profit!

But opportunity doesn’t equal ease. Every decision comes with a price extending beyond the financials. Let’s say you want to launch a daily travel blog. Your side hustle invoice will include the time and creative energy it takes to write, publish and market the blog. You’ll also have some hard costs, such as website hosting, image editing and research. You might take the physical cost into account, such as neck and back pain from extended sedentary time. Don’t forget the mental and emotional toll of the inherent risk that side hustles bring. You’re willing to pay this invoice and march onward.

Fast-forward six months. Maybe the money isn’t flowing like it once was. Maybe the hustle feels stagnant. Maybe you’re just not as excited as you were six months ago. That’s part of the entrepreneurial grind, right? An obstacle is simply an opportunity to push through, go around or leap over. By definition, those who launch side hustles must, well, hustle. This is what you signed up for, right?

But maybe you have a feeling growing deep inside you. It whispers to you in the middle of a sleepless night about missed birthday parties, date nights and free time. You can’t remember the last time you did absolutely nothing at all. The idea of ditching your hustle sounds enticing, and terrifying. You’re used to the extra money. What would your family think? How would it affect your reputation? How can you be sure that ending your side hustle is the right move when success could be just around the bend?

The answer of whether to end your side hustle is not an easy or straightforward one. Just as the decision to start your hustle was one born of risk and gut feelings, so also is the decision to end it. There are hundreds of factors at play, but they can ultimately determine one thing: Is your side hustle still worth the mental, emotional, physical, financial and social investment?

To further break down this idea, consider the following questions. Spend time alone with them. Journal about your answers. Talk to trusted friends and family.

  • You started your hustle for a reason. Do you still believe in that reason? 
  • Where do you see your side hustle six months from now? 
  • Which parts of your side hustle do you enjoy the most? Least? 
  • What are your first thoughts when you wake up in the morning? Before you go to bed? 
  • How would you rate your health—mental, emotional and physical—compared to six months ago? 
  • How would you compare your relationships now with your relationships prior to launching a side hustle?
  • How much of your time is dedicated to your side hustle versus other endeavors? 
  • How much free time, if any, do you have every day? How do you spend it? 
  • If money and time were no object, what would you do? Not do?

Quitting a side hustle can feel like admitting failure, but it can also be the most healing thing you do for yourself. Identify your true priorities and then adjust your life to those priorities. A side hustle should never be something you adapt to, but rather something adaptable to you.

Learn from three side hustlers who found that folding, albeit difficult, was ultimately rewarding and often led to bigger and better things.

Giuseppe Frustaci

Founder of Stick Shift Driving Academy

I was user No. 3553 on Airbnb, having signed up only a few months after it launched. At one point I was hosting three properties in Boston and earning a comfortable income. But in 2016 I started winding it down and by August 2019 I was out.

There’s simply an income ceiling for Airbnb hosts. Developing more skills was neither significantly profitable nor emotionally fulfilling. I could become the best host with the most efficient process and greatest customer service skills, but that investment wouldn’t scale. I also stopped enjoying the work itself. There was a time when I enjoyed meeting the people and I derived meaning from helping people. But then it became a job and I just didn’t have a love for it anymore. 

I started a manual transmission driving school while hosting and grew it to 87 locations throughout the country. Growing that business forced me to develop all sorts of skills and knowledge that satisfied my curiosity

Getting out of being an Airbnb host has been a mixed bag. I’ve had significantly more time and energy to focus on my growth opportunities, but letting go of certain income and easy work for uncertain income and challenging work has been, well, challenging. I was anxious after letting go of my backup plan. But stronger than the anxiety was the certainty that I was making the right decision. I never second-guessed it.

Mike Miller

Founder and Editor-in-Chief of Wilderness Times,  
Fort Lauderdale, Florida 

I wanted to make more money, so I started freelance writing. I did this consistently for six months to build a book of business. I quit because I was overworked and underpaid—I was exhausted.

I was making money, but the revenues were much lower than I expected. I could’ve kept going, but there was one problem: I was miserable. The side hustle no longer felt like a hobby. It became a job. I was constantly working 12-hour days. I wasn’t sleeping well due to stress, and I found myself having a few too many beers to unwind. That’s when I knew I should stop.

It was tough. At first I felt like a failure. It was hard to give up. I changed my side hustle from freelance work to running my own website. It’s 100 percent more fun and relaxing, and I absolutely love it. I make my own schedule and my own decisions. I don’t have a client barking orders at me 24-7. Instead, I make the rules. 

My advice? Do something you could see yourself doing for a long time. Don’t do contract work unless you set clear expectations to your client about deadlines and workload. Choose running your own business over doing freelance work for someone else’s business. Trust me.

Melanie Oates

Speaker, Special Needs Parenting Advocate and Founder of Here for a Reason, Inc, Washington, D.C. 

I have run my side hustle, TwinMomHair, an in-home braiding salon, for 20 years. On Dec. 31, 2019 I closed the doors to my side hustle to focus on raising my children, growing my new business venture, the nonprofit I founded and my speaking career.

During those 20 years, I graduated from high school and college. I got married, had a set of twins, got divorced and became a single parent. I knew the salon was no longer valuable when I experienced a level of burnout like no other. Both of my children are special needs, so the demand as a single parent while running a side hustle was at an all-time high.

The decision to close my salon has been bittersweet. I’ve made so many connections as a stylist and so many clients were inspired by me and my grind while raising my children.

My advice to other entrepreneurs in similar situations is to trust your instinct. If your passion starts to turn into a problem, take that as a red flag. It may be a sign that you either need to focus on something else, or let something go so you can continue the grind.

Turning your passion into profit Read next: 10 Tips for Pursuing a Side Hustle

http://wordpress.com/refer-a-friend/RNlRO6gsz3AkwOnW0Wo3
Make These 5 Commitments to Become a Great Mentor

become a great mentor

Teddy Roosevelt once had a little dog that was always getting in fights and always getting licked. Somebody said, “Colonel, he’s not much of a fighter.” Roosevelt replied, “Oh, he’s a good fighter. He’s just a poor judge of dogs.”

Leaders must be good at judging others’ potential and finding and developing more leaders—good at discerning where a person is, knowing where he or she is supposed to go and providing what they’ll need when they get there.

The bottom line in any successful business or organization is that no one person can do it alone. If you really want to be a great leader, you must establish a great team. A lot of people mistake that to mean they need followers, and they believe the key to their leadership is gaining more followers. But the best leaders surround themselves with other leaders. Not only is their burden lightened, but their vision is carried on and enlarged.

This is why I am such a believer in the power of mentorship. A mentor is someone who teaches, guides and lifts others up by virtue of his or her experience and insight. A mentor is someone with a head full of experience and heart full of generosity that brings those things together for another person.

Wherever you are on your leadership journey, I’ll bet there is someone a bit earlier in their own who could use your mentorship. You owe it to them and to yourself to offer it. What is the point of success if we cannot share it with others?

Judging who you will share your time and experience with is of the utmost importance, because it will give your efforts the greatest odds of providing value. Here are some guidelines for selecting the right people to mentor and develop:

1. Select people whose philosophy is similar to yours.

It will be difficult to develop someone whose values are too different from your own.

2. Choose people with potential you genuinely believe in.

If you don’t believe in them, you won’t give them the time they need. And before long they will discern your lack of confidence in them. Belief in their potential, on the other hand, will empower them. Some of the nation’s greatest professional athletes have come from tiny colleges that receive no publicity. All those ball players needed was for pro scouts to recognize the potential that the right opportunity could bring out. The secret of mentoring in any field is to help a person get where he or she is willing to go.

3. Determine what they need.

Determining what potential leaders need involves looking at their strengths and weaknesses objectively. Their strengths indicate the directions they need to go, what they can become. Their weaknesses show us what we need to help them improve. Encouraging them in their strengths and helping them overcome their weaknesses will move them closer to reaching their potential.

4. Evaluate their progress constantly.

People need feedback, especially early in their development. Ben Franklin said, “The eye of the master will do more work than both his hands.” He knew that leaders’ ability to evaluate is their greatest strength. An honest mentor will be unbiased. If necessary, he or she will encourage a person to stay on course, to seek another direction, or even to enter into a relationship with another mentor.

5. Be committed, serious and available to the people you mentor.

The development of potential leaders around you will be a reflection of your commitment to them: Poor commitment equals poor development; great commitment equals great development.

By personalizing each person’s journey through your devoted mentorship, you are helping him or her to maximize their potential. You are giving them a chance to discover their true purpose. You also maximize their contribution to you and your organization, if they’re already part of your team.

Most people agree that nurturing is important to the development of children. However, they often fail to see its importance in the workplace. They assume that potential leaders will nurture themselves. If we as leaders do not nurture the potential leaders around us, they will never develop into the types of leaders we desire. As Ralph Waldo Emerson said, “It is one of the most beautiful compensations of this life that no man can sincerely try to help another without helping himself.”

When you nurture other people through your mentorship, everyone wins.

Read next: A Letter to the Best Mentor: Thank You for These 5 Essential Career Lessons

http://wordpress.com/refer-a-friend/RNlRO6gsz3AkwOnW0Wo3
Getting Your Finances Back on Track After Quarantine

An open front door to a house.

Life as we knew it came to a screeching halt because of the coronavirus pandemic. But now things are slowly starting to open back up again, and that means the quarantine and #QuarantineLife is ending for millions of Nigerians who have been cooped up in their homes for weeks.

Some folks will be getting out of quarantine faster than others, but most states have already reopened or plan to start lifting some of those restrictions put in place to stop the spread of COVID-19 in the 9.JA.1

What does that mean for you? Well, first of all, you’re going to have to start wearing pants again. Bummer. But this is also a good time to take a fresh look at your financial situation. Here are six things you can do to get your finances back on track as you emerge from your quarantine cave:  

1. Reassess your current situation.

When this crisis began, you might have gone into “survival mode” and focused on taking care of the Four Walls—that’s food, utilities, shelter and transportation—and nothing else. You canceled your Netflix account, told the credit card companies to wait their turn, and called off that vacation you had on the books for months. Start budgeting like a boss with our FREE budgeting tool!

It was tough, but you did what you had to do! And now as the quarantine winds down, it’s time to take a step back and look at your current situation with a fresh pair of eyes. That way, you can make decisions that make sense for your situation! 

Are you still out of work, or feel like your income isn’t very stable? Then you might need to stick with the Four Walls for a little longer—at least until you can get your income situation sorted out.

But if you still have your job (or got a new one) and feel like you’re in a secure situation, it might be time to start attacking your financial goals again—whether that’s getting out of debt or saving for a down payment on a house.

Bottom line:

  • Make sure your income is stable. You may have changed jobs and that’s fine—as long as you have a steady paycheck and things are stable.
     
  • Remember, facts Buhari fear. Take a deep breath and see if the facts are on your side.
     
  • Before you emerge from financial quarantine, make sure you’re caught up on your bills and debts so you’re not adding interest charges and penalties.

2. Revisit your monthly budget.

There’s no denying it: It’s been a weird few months. And if you were stuck at home during quarantine, your budget probably felt really out of whack.

Working from your living room with nowhere else to go, you probably went weeks without having to fill up on gas. On the flip side, you probably spent more on toilet paper and hand sanitizer in the last two months than you have in your entire life!   

Now as things slowly shift back to “normal,” whatever that looks like, you might need to start adjusting your budget back to where it was pre-coronavirus as you start driving more and getting back into the swing of things.

But maybe this quarantine has helped you realize that some things shouldn’t go back to normal. Maybe all those banana bread recipes you baked during the quarantine have inspired you to avoid eating out as much as you did before. And those free workout videos on YouTube and walks around the neighborhood helped you feel the burn without the gym membership burning a hole in your budget.

The point is that you have a chance to pick and choose what comes back into your monthly budget and what stays out—don’t waste it!  

3. Get back on the Baby Steps.

No matter where you were on the Baby Steps when things shut down, you probably needed some time to pause as you navigated through life in the land of COVID-19.

If you’ve been chomping at the bit to get back to attacking your debt snowball with gazelle intensity or saving for retirement again, now might be the time to get on it—especially if you still have your job and feel like your income is stable:

  • If you’re on Baby Steps 1–2: Once you have at least NGN, 389000 saved up, get that debt snowball rolling again so you can attack your debts as fast as you can. Having debt lying around will leave you financially vulnerable if another crisis or emergency hits, so get it out of your life once and for all.
  • If you’re on Baby Step 3: With millions of Nigerians losing their jobs or getting furloughed, many folks had to dip into their emergency funds to keep things going. If you’re back at work and have a steady income, it’s time to get that emergency fund back up to 3–6 months’ worth of expenses.
  • If you’re on Baby Steps 4–7: Whenever you see a storm coming—whether it’s an impending job loss or a global crisis—it makes sense to pause contributions to your 401(k) and IRA, deposits to the kids’ college funds or making extra payments on the house. That way, you can pile up a little more cash for the essentials. But now that the clouds are starting to break, you might feel comfortable picking up where you left off.  

And if you’ve kept the money from your stimulus check in a holding pattern within your bank account, you might feel comfortable enough to throw that money at whatever Baby Step you’re on! 

4. Make a plan for action items you put off.

Maybe you had plans to put new tires on your car, take your kids to the dentist or install a new HVAC system earlier this year. But then the pandemic happened and, all of a sudden, those things on your to-do list couldn’t get crossed off just yet.

But as businesses start opening up again with social distancing measures in place, you might be thinking about pulling the trigger on some of those action items you’ve been putting off. Just make sure you have them accounted for in the post-quarantine budget.

If you feel like your situation is stable and you have the money budgeted for those repairs, appointments and purchases (without dipping into your emergency savings), then go for it.

5. Keep a lot of cash on hand (just in case).

If there’s one thing the pandemic has taught us, it’s that we need to be prepared for whatever life throws our way. Today, it’s a global pandemic. Tomorrow, it might be an invasion of murder hornets (look it up).

If you piled up cash during the crisis, good job! If possible, it still might be wise to have a little extra cash in your emergency fund for the rest of the year—just in case. Having a large pile of money in the bank gives you flexibility to stay calm and turn almost any emergency into an inconvenience.

6. Check in with your financial advisor.

A lot of things have changed in the last few months. Now that things are straightening out, it’s a good time to check in with your financial advisor. Not only can they go over your investments with you, but they can also offer guidance on any financial plans that may have changed or temporarily shifted.

If you had a job loss or change and have a 401(k) from a previous employer that needs rolling over, they can help you get that squared away. And they can help you take a step back and look at the big picture.

Don’t have a financial advisor or investment professional? An investment professional like a SmartVestor Pro can help.

Find a SmartVestor Pro in your area today!

3 Ways to Strive for Financial Freedom—Even During a Pandemic

financial freedom

We live in uncertain times. The deluge of depressing news only reminds us of the many things that are out of our control.

Amidst so much uncertainty, it may seem strange to ask, “How can I achieve financial freedom?” We can’t even guess what’s going to happen in the next week, so how could we possibly predict 30 or 40 years from now when many of us will retire?

In reality, your financial future is as much within your grasp now as it always has been. The first step toward achieving financial freedom is accepting what you can control instead of worrying too much about what you can’t—although worry is perfectly normal during a time like this.

Set aside pressing concerns about the pandemic for a moment, though, and consider the many factors that always seem to threaten your financial freedom. Taxes, the markets, interest rates—there are plenty, and you have very little control over most of them. It’s easy to spin your wheels worrying about these unknowns, but it doesn’t get you anywhere.

What you can control is your plan for the future, your habits and the steps you will take to achieve financial freedom. These are the things that should hold your attention rather than the fluctuating circumstances of your life.

Recognize the Obstacles

While the COVID-19 pandemic represents a unique challenge, the truth is that there are always obstacles in our way and excuses at the ready. There are many ways to achieve financial freedom, but they all start with recognizing and responding to the things that tempt us to throw in the towel.

There are plenty of things fighting to pull our attention away from long-term goals. The Instagram culture, for example, creates an insatiable hunger to keep up with everyone else, and this desire has pushed 40% of millennials into debt. Our smart devices make instant gratification seem reasonable all the time, so much so that 41% of respondents to a 2017 poll said technology made them more impatient than they were five years prior.

Often, though, the easiest excuse is simply the fact that retirement—a time when you need true financial freedom—seems so far away. It’s tempting to think that you’ll have a bit more to put away next year or that your home remodel is more urgent than saving. No matter the justification, these distractions are pulling you away from your financial freedom goals.

Ways to Achieve Financial Freedom

Ultimately, there will always be things you cannot control, but you can take specific steps to achieve financial freedom—regardless of your situation or what’s happening in the world—by taking control of your budget. Here are three ways to do just that:

1. Put your goals first.

The best path to financial freedom, as with any other dream, begins with concrete goals. What are your financial objectives five, 10, 20 and 30 years out? Where do you hope to send your kids to school? When do you want to retire? Get these goals on paper, writing out the approximate time in which you’d like to achieve them and how much they’re projected to cost.

As you start to plan for your goals, you’ll need to have a good handle on your budget. Instead of pinpointing where every dollar goes each month, I’ve found it’s easier to set up a reverse budget. For this kind of budget, you’ll need to determine how much you need to save for your goals and then set those savings on autopilot. Once your savings are set up, whatever money is left can be spent however you’d like—housing, food, going out, etc.

Once you’ve planned your goals and budget, you can build a saving and investing strategy around them. If your goal falls within the next three to five years, for example, consider setting aside those funds in something very liquid (e.g., a money market account). If your goal is five to 10 years away, however, you could consider a moderate investment allocation such as 50% in stocks and 50% in bonds. Finally, if your goal is 10 to 15 (or more) years away, you could potentially take more risk and invest 70% in stocks and 30% in bonds—or even 80% in stocks and 20% in bonds. Note that you’ll want to make more conservative investments as you get closer to your goal date.

Determining how much to save for long-term goals can be daunting and challenging, which is why it might be helpful to meet with a financial advisor. A financial advisor can help you decide how much of your assets to put into stocks and bonds in addition to developing guiding principles for how you invest. When you have a set strategy in place, it’s easier to stay the course and reach your goals—even during difficult times.

2. Have a safety net for emergencies.

The COVID crisis is a poignant reminder of the importance of an emergency fund. You can’t control what happens, but you can plan ahead and be ready for anything. For everyone who has received or will receive a stimulus check from the government, I would suggest using that money to take care of basic needs like rent, utilities, groceries, etc. If you have any money left over, keep it in cash for emergencies. Even though it’s a great time to buy into the market, you shouldn’t invest that money if there’s any chance you’ll need it in the next couple of years.

Aim to build up enough savings in your emergency fund for three to six months of living expenses (or more, if your income is variable), which will allow you to weather a bout of unemployment or other unforeseen circumstances.

Emergency funds should be very liquid and safe, so keep them in a secure account like an online money market. Even better, an online money market account will earn a little more than if you kept the money in a savings account at a brick-and-mortar bank. The process of building an emergency fund will differ depending on your stage of life and current assets. When you’re just starting out, it may not be possible to have six months of expenses on hand. An excellent way to build your fund up is to designate a certain amount from your paycheck each month that goes into whatever separate account you choose.

By the time you retire, it’s best to have as much as 18 to 24 months of net expenses on hand. For example, say your expenses are $150,000 a year during retirement; if you get $30,000 from Social Security and $50,000 from a pension each year, you’d have $70,000 of net expenses. In this scenario, a target cash reserve of $105,000 to $140,000 during retirement would be a great buffer. This approach also helps prevent the need to sell stocks when the market takes a nosedive.

3. Allocate for your future.

Saving for retirement should always be a significant part of your financial freedom plan, so you need to account for it in your budget. Contributing to a company retirement plan—such as a 401(k) or 403(b)—an IRA, or a Roth IRA is a great place to start. It’s important to note that traditional 401(k) and IRA account contributions are tax-deductible. Since you get an upfront tax deduction, you must pay taxes on anything you withdraw during retirement. Conversely, Roth 401(k) and Roth IRA contributions are made with after-tax money and thus can be withdrawn tax-free during retirement.

Now might be a great time to make those contributions. Doing so while the market is in flux means you can potentially buy more shares with your dollars. Be sure to choose low-cost ways to invest (such as index funds or ETFs) while maintaining a diversified portfolio to help you manage risk.

To do this, your portfolio should include both large and small U.S. companies as well as those outside the U.S. You might also add short-term, high-quality bond funds. These are a good buffer in portfolios and can help reduce risk. It’s much better—and will have a higher payoff—to take risks on the stock side.

And remember that you can start with baby steps. I worked with one client who was just starting out and feeling overwhelmed with the thought of investing. I helped her set up a small deduction from her bank account that was invested into a Roth IRA. While the amount was minimal, she realized she was able to live without that money and slowly increased it each year. Starting small, as my client did, and celebrating wins along the way gives you the boost to keep track of your spending and save for the future.

Start Planning Early

Don’t put off your finances until you feel like you finally make enough money to create a plan. If you start the habit of planning and budgeting when you’re young, you’ll be able to expand your savings rapidly as your income grows. And there are so many great resources that can help, like BrightPlan, Mint and EveryDollar.

The question, “How can I achieve financial freedom?” is as relevant now as it ever has been. If you find yourself struggling to come up with an answer, shift your focus to what you can control. You might be surprised by how far you can get with your attention in the right place.

Read next: 16 Timeless Truths of Financial Freedom

Financial Education in 17 Definitive Lessons by robert kiyosakiA Different Financial Education (in 17 Definitive Lessons) From Rich Dad Program

How I would teach financial education if I ran our schools

What is financial education? That’s a good question, and one that has many different answers depending on who you talk to.

For some, financial education means teaching kids how to save money, balance a checkbook, and use a credit card responsibly.

For others, it means teaching how to invest in the stock market and manage a 401(k).

ONLY 13% OF AMERICANS WERE TAUGHT ABOUT INVESTING IN SCHOOL

Whatever your definition of financial education, it’s clear that there’s one thing we can all agree on—financial education is nearly non-existent in our schools.

A recent survey by Ipsos shows that only 13% of Americans were taught about investing in school. The same people surveyed believe overwhelmingly that financial literacy should be taught in school (87%), and that it should start as early as Middle School (72%).

This begs the question, what would it look like to teach financial education in our schools?

As a financial educator, if I ran the school system, I would begin by creating a financial literacy program that included the following 17 financial lessons. Even if you’re not in school anymore, these would be valuable lessons to study and learn on your own as part of your financial education.

Financial literacy for beginners

Lesson 1: The history of money

It’s important to understand how money works, and part of doing that is by studying how it’s worked in the past. Money has progressed over the centuries from something pretty simple, like bartering, to something pretty complicated, like derivatives. It’s gone from being an object to an idea, so it’s not tangible and intuitive. It’s important to study money to grow rich. Some dates that are important:

1903 – Rockefeller’s General Education Board takes over the U.S. education system

1913 – The Federal Reserve is formed

1929 – The Great Depression

1944 – The Bretton Woods agreement

1971 – Nixon takes the dollar off the gold standard

1974 – Congress passes the Employee Retirement Income Security Act

If you want to learn more about how these the history of money is impacting your life, check out this post about fake money.

Lesson 2: Understanding your personal financial statement

My rich dad often said, “Your banker never asks to see your report card. A banker wants to see your financial statement—your report card when you leave school.”

One of the foundational elements of financial literacy is understanding how to read and understand a personal financial statement.

Click here to learn more about the personal financial statement and how to begin using one today.

Lesson 3: Know the difference between an asset and a liability

One reason many people are in financial trouble is because they confuse liabilities with assets. For instance, many people think their house is an asset when it’s really a liability. A simple definition of an asset is anything that puts money in your pocket. A simple definition of a liability is anything that takes money out of your pocket.

Discover how to transform your liabilities into assets.

Lesson 4: Seek cash flow… then capital gains

Many people invest for capital gains, meaning they’re betting on the price of something to go up. Unfortunately, today, many people aren’t winning on those bets. Investing for capital gains is akin to gambling, only not as much fun. Instead of investing for capital gains, the wealthy invest for cash flow and capital gains are icing on the cake, if they do happen.

Get a deeper understanding of the differences between cash flow and capital gains here.

Lesson 5: Three types of income

Not everyone earns money through a paycheck. In fact, my rich dad taught me that there are three types of income: earned, portfolio, and passive.

If you have a job and receive a paycheck, you make money through earned income. If you make money through the sale of capital gains, you make money through portfolio income. The third type of income, passive, is when you make money regardless of whether you work or not.

Gain a deeper understanding of the different types of income here.

Lesson 6: The CASHFLOW Quadrant

According to my rich dad, there are two types of people, those who view the world through the two different sides of Rich Dad’s CASHFLOW Quadrant.

To summarize, on the left side of the quadrant are Es and Ss. They pay the most in taxes and trade their time for money. And each has a different mindset.

On the right side, however, are the Bs and is. They pay far less in taxes but create (or invest) in assets that make money for them even when they’re sleeping.

Dig deeper into the CASHFLOW Quadrant here.

Lesson 7: Savers are losers

In 1971, President Nixon changed the rules of money. That year, he closed the gold window instantly turning our dollar (which was backed by gold) into a currency. This was one of the most important monetary shifts to happen in modern history, yet few people understand why.

The reason savers are losers is because of this change. The value of the dollar continues to lose its value because of inflation. Basically, what your money can buy in the future is less than it can purchase now.

Check here if you want to better understand why saving is for losers.

Lesson 8: Your wealth number

True wealth isn’t determined by your net worth or how big your bank account reads. True wealth is determined by your wealth number.

As we discussed above, if you are making money through passive income and it’s more than you spend every month, you have an infinite wealth number.

Figure out your wealth number here.

Lesson 9: The difference between fundamental and technical investing

Fundamental investing is the process of analyzing a company’s financial performance, and that begins with understanding a financial statement. Technical investing is measuring the emotions or moods of the markets by using technical indicators. You can invest successfully doing both types of investing, but both take commitment and continued financial education.

Learn the differences between fundamental and technical investing here.

Lesson 10: Know how to measure an assets strength

There are four asset classes: Business, real estate, paper assets, and commodities. To grow rich, you must study these classes, choose what is best for you, and work towards becoming an expert.

There is no shortage of opportunities in the world of investing. The question then becomes, which investments are worth pursuing? A key component of a full financial education is understanding how to measure whether an asset is strong or not. One of the best ways to do this is to refer to the B-I Triangle, which looks at an asset’s full properties: Team, leadership, mission, cash flow, communication, systems, legal, and product.

Lesson 11: Know how to choose good people

Partners are crucial to business success. My rich dad used to say, “The best way to know a good partner is to have had a bad partner.” You need to learn from every interaction. A good deal can blow up if you have a bad partner. So choosing partners and team members well is crucial.

Lesson 12: Know when to focus and when to diversify

Ideally, you’ll want to be diversified in all four asset classes, but you’ll want to focus on becoming an expert in one at a time. An old adage is that if you try to please everyone, you’ll please no one. The same could be said for investing.

Lesson 13: Minimize your investment risk

In investing and business, there is always an element of risk. A smart investor knows how to minimize risk by hedging. There are a number ways you can do that within each asset class. Study up on ways to minimize risk in your chosen asset class.

Here are three reasons why investing can be risky, and what you can do to minimize your risk.

Lesson 14: Make more money with taxes

My rich dad would always tell me, “It’s not about how much you make, it’s about how much you keep.” Taxes are your biggest expense. That’s why it’s important to your financial education to understand how you can best limit that expense.

A financially intelligent person understands how to use the tax code to his or her advantage. Go here to learn more about how you can save on taxes.

Lesson 15: The good, the bad, and the truth about debt

As many of you know, there is good debt and there is bad debt. The key to using debt is knowing how to borrow wisely and how to pay back the money. Without a solid plan to pay back debt, you’ll soon have no credibility. A solid financial education will include understanding debt and how to pay that debt back.

Lesson 16: Know how your wealth is stolen

There are four things that steal your wealth: Taxes, debt, inflation, and retirement. A proper financial education will stress understanding how to use these wealth-stealing forces to make money rather than lose money.

Don’t let these thieves steal your money. Put a stop to them here.

Lesson 17: Know how to make mistakes

It’s impossible to learn without making mistakes along the way. The key is to learn the lessons of those mistakes, and not let them take you out of the game. Look at failure as a learning opportunity.

How to get a financial education

We covered many of the truths that we hold dear at Rich Dad and I’ve given you many different avenues to increase your financial education.

It doesn’t matter what road you take. What’s important is that you start. Here Is What will fuel your future? http://wordpress.com/refer-a-friend/RNlRO6gsz3AkwOnW0Wo3
Happiness Is an Everyday Job Keep It Up

Happiness Is an Everyday Job

When we think about a happy life, it can be tempting to think on a grand scale, to consider major events like birthdays, weddings or the birth of a child, but the truth is that days like that come around just once in a great while, maybe making up a week or two of each year. Instead, our weeks, our months and our lives are made up of normal days, distributed across workdays and weekends for the most of us. As a result, the true building blocks of a happy life look a lot more routine.

At this point, enough happiness research has been conducted that we can generalize a bit about some of the ingredients for a happy life. At a basic level, we need connection, a sense of meaning and the energetic support of a healthy body—or, relationships, projects, and sleep, diet and exercise. The good news is that unlike the wild destination weddings or over-the-top baby showers we see on social media, these ingredients are achievable for most people.

While it’s perhaps commonsensical to say that if we want to have a happier life, we should work on creating happier days, some common beliefs can get in our way. First, and most insidious, is the “everybody’s working for the weekend” mindset. With all respect to the band Loverboy, this is a terrible life philosophy. The work hard, play hard strategy that has us locating happiness in the weekend or solely during vacations has bad numbers behind it. After all, in a 52-week year, only 104 days are weekend days; that’s leaving a lot of the days of the year consigned to misery. Over a life, that’s a bad proportion. 

The second, related belief that gets in our way is that happiness has to be carved out. While there’s a kind of truth to this, as in the case of taking an enriching art class, it’s also the case that already-existing time chunks can be converted from relatively mundane or even soul-sucking to happiness-inducing.

For example, on a recent episode of her Before Breakfast podcast, time-management expert Laura Vanderkam talks about renovating the lunch hour. After all, as she points out, over the course of a year, five hours a week adds up to 260 hours, the equivalent of over 30 eight-hour workdays. That’s quite a bit of time to invest in building relationships with colleagues, exercising, reading novels or even writing a novel. Any of these activities is more likely to boost an overall sense of having a meaningful and happy life than the typical activity of munching a sandwich while mindlessly scrolling email.

This general principle can be applied to many of our daily routines. For example, people tend to be made unhappy by their commutes in and out of the office, an event that happens 10 times a week. With some forethought, though, this time can be reclaimed. Ride a train or a bus for your commute? Maybe you could set a reading project for the year. Drive a car? What about committing to learning a new skill by listening to podcasts on the topic? Walk? How about a standing phone call with a family member or friend who lives far away?

The same idea can be applied to chores. What about creating a family tradition that laundry folding involves singing show tunes together? Maybe every Friday is new recipe night, with each season of the year involving mastering a new national cuisine.

There’s also something to be said for intentionally committing new time to a more ambitious happiness-building project. Weeknights can tend to take on a same-y quality of dinner and television before bed, and Sunday night is particularly dread inducing. In fact, in a Journal of Social and Clinical Psychology article,the researchers found an overall sense of better well-being among their subjects on weekend days. Making the decision to take a class, form a monthly book club or join a recreational sports league is not going to overwhelm most people’s schedules, and a meaningful social or learning commitment can create a midweek bright spot or transform a Sunday evening into a favorite time of the week.

Making better choices about how we spend the days that make up the bulk of our adult lives is a way of taking back autonomy, which itself is a happiness-inducing practice. Given the choice between days that blur together and days that increase our sense of agency and overall happiness, who wouldn’t choose the latter?

Related: 3 Ways to Prioritize Your Happiness

25 Ways to Get Out of Debt

25 Ways to Get Out of Debt

Paying off debt can be frustrating and confusing if you don’t have the right plan. For more than 25 years, Dave Ramsey has taught people a step-by-step approach to slashing their debt called the 7 Baby Steps. 

On Baby Step 1, you save $1,000 in a starter emergency fund, and on Baby Step 2, you pay off all your debt (except the house) using a method called the debt snowball.

How to Pay Off Debt: The Debt Snowball Method

  • List your debts from smallest to largest regardless of interest rate.
  • Attack the smallest debt with a vengeance while making minimum payments on the rest of your debts.
  • Repeat this method as you plow your way through debt. 

Look, Baby Step 2 takes a few months to finish for some people and a few years for others. So if you’re on this step and laser focused on paying off that last debt, it’s possible the grind is starting to become . . . well, a grind. Maybe you’re exhausted and feel like it’s going to take forever to become debt-free.Hold that thought, because we’re here to give you our top 25 ways to get out of debt so you can be debt-free even sooner.

How to Get Out of Debt With Frugal Living and Smart Shopping

1. Start couponing.

You’ve probably heard this a thousand times—but are you doing it? You can save a ton of money just by showing a coupon to the cashier. Just be sure you’re using coupons for products you already buy, otherwise you could end up overspending on items you’ll never even use. That’s how you end up with 10 bottles of spicy mustard sitting in your pantry.

2. Try consignment shopping.

Kids grow out of clothes at the speed of light (or so it seems). And let’s be real: It’s not worth it to go into debt for your 2-year-old’s ever-changing wardrobe. Check out your local consignment stores that sell pre-loved outfits in good condition. If you’d rather shop online, no problem. Sites like thredUP and Swap.com are great resources to get adult and children’s clothing at a fraction of the cost.

3. Cut the cable.

Welcome to this millennium, where you can watch most of your favorite shows online. If you haven’t cut the cord yet, do it! Put that $100 cable bill toward your debt each month and watch just how quickly your debt snowball starts rolling.

4. Stop going out to eat.

We get it. Going to a restaurant or hitting up the drive-thru is so much easier than making meals at home. But while you’re enjoying the freedom of not having to cook for those picky eaters, you’re spending way more eating out than you would by eating in. Want a creative way to socialize and share a meal? Invite friends over for taco night instead of meeting up at a restaurant. And hey—if you want to splurge for guac, we’re not judging.

5. Break up with your barista.

If you don’t know where all your money’s going each month, we’re pretty sure your favorite coffee shop can find it for you. Brewing your own coffee at home is a simple way to save money fast.

6. Visit the library.

Remember libraries? They have plenty of books and movies you can check out—for free! Your wallet has never loved movie night more than it does now.

7. Plan your grocery trips.

Make a list and stick to it! Use the calculator app on your phone while you browse the aisles to make sure you’re sticking to your budget. Do impulse items always end up in your cart? Try ordering your groceries online and then picking them up curbside at the store. Oh, and don’t ever shop on an empty stomach!

8. Avoid expensive hobbies.

Do you really have $200 a month to spend on golf? Are you serious? But it’s not just the golfers out there who need to rethink their club dues. Do you spend a ton at craft stores but never get around to starting your project? Home improvement stores can also cost you several Benjamins in one visit.

9. Ditch the gym membership.

You can still go for a run outside—for free. Gather some friends and start a running club. Or do those fancy HIIT workouts at your local park. Listen, it’s a free country. Well . . . mostly.

10. Find free entertainment.

Put a spending freeze on your entertainment costs for a little while. This means no going out to the movies, concerts, mini golf, bowling or whatever you do for fun that costs money. Instead, challenge yourself to find free ways to stay entertained. Take the kids to the park, go for a walk or a hike, enjoy a free concert, or look for a free event in your community.

Dave Ramsey’s Basic Tips for Getting Out of Debt

11. Start a side gig.

Starting your own business has never been easier! Do you have a knack for making things? Sell your products online. Are you an animal lover? Take up dog walking or pet sitting. Do you have a good eye and a nice camera? Start taking on clients for photo sessions. Christy Wright’s Business Boutique is a great resource to show you how you can turn that hobby into a serious money-making machine!

12. Get a part-time job.

Not into starting your own business? Then consider becoming a driver for Lyft or Uber. A pizza delivery job at night could also bring in extra money. You can even deliver other types of food in your spare time by working for places like Uber Eats or Grubhub. Sure, you’ll have to put aside your pride and give up some nights and weekends of downtime. But that’s a small sacrifice for extra cash in your pocket.

13. Sell the car!

The average monthly payment for a new car is $554.1 That’s just outrageous! Think about how much faster your debt snowball could move if you threw that $550 at it every single month.

14. Cut up your credit cards.

Shred ’em. Burn ’em. Shoot ’em. You’ll never get out of debt until you stop making debt a way of life.

15. Use the envelope system.

When you pay with cash, you actually feel your money leaving your hands. Ouch! Nobody likes that. People tend to spend less when paying in cold, hard cash. With the envelope system, you’ll see that cash going down so you can keep track of how much you’re spending.

16. Stop investing.

Yep, you read that right. And yes, we even mean stop contributing to your 401(k). Right now, you want all your income to go toward getting out of debt. Once you’re debt-free and have saved three to six months of expenses in an emergency fund, then you can resume your contributions. By then you’ll be on Baby Step 4 and can start putting 15% of your income toward retirement.

17. Ignore your broke friends.

Stop trying to keep up with the Joneses! Remember, you’re living like no one else now so that later you can live and give like no one else. In 20 years, you won’t have a financial worry in the world while everyone else will still have car loans, mortgages and credit card bills.

18. Make a budget!

Budgeting should be easy and—dare we say it—fun! Use our free budgeting app, EveryDollar, and focus your money on what matters: day-to-day spending, those pesky debts and wealth building.

19. Tell the kids you’re on a budget.

When it comes to money, the kids can be a worse guide than your stomach. Be open with them about what you do and don’t have room for in the budget. And remember: Never be afraid to use that magic word no.

20. Listen to The Dave Ramsey Show.

Listening to the show will encourage you when you feel like you aren’t making progress. Every day, Dave helps millions of people across the country find hope and make a plan for their money. Their successes will inspire you to keep moving forward. 

Other Creative Ideas to Get Out of Debt

21. Ask for a raise.

What do you have to lose? Michael Jordan always says, “You miss 100% of the shots you don’t take.” Thanks, Mike.

22. Learn to say no.

Make it a new part of your vocabulary. Love it. Embrace it. Because when it comes to spending money, you’ll be saying it quite often.

23. Sell items on Facebook Marketplace or Craigslist.

One person’s trash is another person’s treasure. Dig through your kids’ rooms and the abyss of your closet to find things you can part with to make some quick cash.

24. Give more.

Wait a minute—give? Yes! Giving changes you. It changes your spirit. Make giving a priority in your budget, no matter what your income is, and you’ll feel like a million bucks.

25. Take control of your money with Financial Peace University.

Financial Peace University is the proven plan that will get you out of the cycle of living paycheck to paycheck. Financial Peace is the membership that will teach you how to pay off debt, budget, save big, and give like no one else. And right now, you can try it free with a 14-day trial!  You’ll get all nine video lessons that break down the proven plan—the 7 Baby Steps, plus other awesome tools and resources to help you get your money on the right track right now! Take control of your money with a FREE trial of a Financial Peace Membership.

But if you’ve already had the opportunity to go through the class, maybe it’s time to lead others through it. It’s one of the best ways to stay gazelle intense (and keep yourself accountable). Take it from us: Watching others change their lives feels pretty darn good.

There you have it—25 ways to get out of debt and breathe fresh air into your debt-free journey. Try a few of these tips and see if they work for you. When you hit a wall and feel like you’ll never figure out how to get out of debt, just keep working the plan! Over time, your dedication will pay off!

How to Improve Your Life in 8 Steps

howtoimproveyourlifeinsteps

“To be excellent we cannot simply think or feel excellent, we must act excellently.” —Aristotle

Improving your life and well-being isn’t something that happens through hopes and flukes. It happens through tenacity and consistency.

Related: 43 Ways to Improve Yourself in Just 10 Minutes​

Your success, happiness and dreams will happen through the quality of your actions and an abundance mindset. Start with these eight steps, and you’ll begin to construct and see an improved version of yourself.

1. Establish a vision.

“The only thing worse than being blind is having sight but no vision.” —Helen Keller

Whether it’s a fitness, business or relationship goal, establishing a vision is key. Your vision serves as your compass and prevents you from getting lost on the path to your ultimate goal. A vision forces you to be specific about what you’re going after, and once you have it, it becomes part of your identity and propels you into action each day.

As you’re establishing a vision, set aside some time to do the “Perfect Day” exercise. Ask yourself these questions and give yourself time to think through the answers.

  • How do I want every day to look?
  • How do I want to feel each day?
  • Whom am I spending my days with?
  • What kind of work am I doing?
  • How do I want to make people feel after being around me?

2. Commit to showing up.

Motivation comes and goes like the clouds passing through our days. It’s not a dependable resource to propel you into action each day. To develop your talent and upgrade your well-being, you have to show up every day, no matter the circumstances.

As the Japanese proverb reminds us, “Vision without action is a dream. Action without vision is a nightmare.” Let your vision serve as your compass while your actions propel you to become a better version of yourself.

At the beginning, it’s understandable to feel a little apprehensive about the journey; fear is normal. But taking giant leaps of action and risk isn’t necessary. Tiny steps and small moments of courage are the only requirements.

Make that call, pitch your idea, ask for that raise, post that first video, ask that tough question, do that first workout, and make that first healthy breakfast. This is how remarkability begins.

All great achievements start with one small action.

3. Don’t try to do it alone.

No one succeeds in this world alone. Players have coaches. Singers have producers and co-writers.

Having support allows you to have someone to be accountable with, to get an unbiased perspective on the development and pursuit of your goals. No one gets immunity from the fear, doubt and uncertainty that pursuing new endeavors presents. It’s pivotal to have a support network to catch you whenever you begin to slip back into your old habits and play small.

Make it a goal today to think of three people who can provide support and accountability for your new journey

4. Embrace the pain, adversity and fear.

Fear is a natural part of life and it’s actually good in certain circumstances. Fear is nothing more than your body trying to protect you. As you’re pursuing a better version of yourself, acknowledge your fear and tell it thanks but no thanks.

Adversity and small failures are nothing but feedback and information for you to use as you proceed along your journey. It’s OK to have butterflies while doing unfamiliar things. But remember, all you need is those 20 seconds of courage to take the leap forward and grow.

5. Play for something bigger than yourself.

“What’s your goal?” I often ask my clients.

“To lose weight,” they might respond.

That’s great, but it’s only scratching the surface. Dig deeper into why you want to pursue your goals.

If you go deeper with your goals and motivation, you’ll see that it’s more layered than you realized. Tapping into this deeper level of motivation for why you want this thing builds endurance. It cements the goal in your mind and your heart. It keeps you on track when distractions will attempt to veer you off course.

6. Learn every day.

When you quit learning, you are left behind. Adopt a student mentality and develop a growth mindset where you’re always becoming better at your craft. One of the most common traits between successful people is their habit of continuous learning.

7. Find time for daily exercise.

Tony Robbins says “motion creates emotion.” The type of exercising doesn’t matter as much as the consistency of doing the habit does.

Your health is the head of an octopus and the tentacles are the other facets of life. Without the head being in an optimal state, the rest of those tentacles aren’t going to operate and function properly. And then you won’t show up as the best version of yourself every day.

8. Reflect, acknowledge and appreciate your current accomplishments.

Ambition is a double-edged sword. On one end, it motivates you to pursue your goals. On the other end, you never feel good enough or that progress is happening because you’re so fixated on the result, which feels so far away.

Try tracking your progress on a daily basis. This allows you to see daily growth for what’s working and what isn’t. After all, what gets measured gets improved.

Journaling is one of the best ways to manifest success, happiness and growth in all facets of your life. Journaling provides clarity over your objectives while also improving your mindfulness, happiness and self-confidence. Writing down three things you’re grateful for each day can teach your brain to look for positive opportunities and shift into an optimist mindset.

Related: 6 Mindset Shifts That Will Improve Your Life

If Your Emergency Fund Can’t Cover Your Emergency? We’re Giving Away Cash! Enter To Win.

7 MINUTE READ

Emergencies—they can hit you out of nowhere. And if you don’t have a buffer of cash between you and all the twists and turns of life, things can get tricky fast. That’s where an emergency fund comes to the rescue—it’s your financial safety net when things go south.

An emergency fund works like a dream if you’ve got enough money saved. But what happens when the emergency is bigger than your savings? What if you wreck your car, lose your job, or have to take a trip to the hospital?

What Is an Emergency?

First off, let’s be clear about what qualifies as an emergency. A sale at your favorite department store is not an emergency. Neither is your summer vacation. Or renovating your kitchen.

No matter what crisis you’re going through, you don’t have to panic. You can be prepared. Here’s what to do for those times your emergency fund isn’t enough to cover your emergency. http://wordpress.com/refer-a-friend/RNlRO6gsz3AkwOnW0Wo3

Large expenses—like new tires for the car or braces for your kids—shouldn’t be emergencies either. You know these expenses are coming, so plan ahead and save up to pay cash. Take control of your money with a FREE trial of a Financial Peace Membership.

True emergencies are unexpected, necessary and urgent. Rear-ending someone on the interstate, cutting yourself while chopping veggies, or suddenly getting laid off are actual emergencies. Emergency funds are for when something serious happens, not for when you just want to treat yourself. So, make sure you’ve got a bona fide emergency on your hands before you decide to dip into your savings.

“A crisis becomes an inconvenience when you have an emergency fund.” — Dave Ramsey

How Big Should My Emergency Fund Be?

Great question! Around here, we stick to the 7 Baby Steps. Baby Step 1 is to save $1,000 for your starter emergency fund. Why? Because you need a cushion to keep you from having to borrow money while you tackle Baby Step 2—paying off all debt (except your house) using the debt snowball method.

We know $1,000 won’t cover every emergency, but that’s why it’s called a starter emergency fund. Once you’ve gotten rid of all your debt, you can move on to Baby Step 3—that’s when you save three to six months of expenses in a fully funded emergency fund.

If you’ve already got an emergency fund (no matter how big it is), go ahead and give yourself a high five! You’re doing better than the 78% of Americans who are living paycheck to paycheck.1 But if you find yourself in a situation that your emergency fund won’t cover, there are ways to get through it without putting yourself in debt.

5 Steps to Take When an Emergency Is Bigger Than Your Emergency Fund:

1. Pay only minimum payments on debt.

There are some rare situations where you need to stop your debt snowball altogether and focus on the here and now. We’re talking about really big stuff like losing a job or getting ready for a baby. In those situations, the best thing to do is only make minimum payments on all your debts for a while and focus on covering your Four Walls: food, utilities, shelter and transportation. Just worry about taking care of the essentials. When life gets back to normal, you can get back to paying off your debts with gazelle intensity.

2. Call and negotiate.

If a family member had to go to the hospital and you’re struggling to pay the bill, call the folks in billing. Ask about discounts or get on a payment plan for medical expenses that you can cash flow over the next several months. When in doubt, ask. Just be persistent, patient and kind. And if possible, pay something up front to show you’re serious about repaying your debt. They’ll usually work with you.

And if you’re not the only one dealing with a specific crisis (like a massive layoff, a natural disaster, or a government state of emergency), see if there are any local nonprofits offering financial or physical assistance (like free food, childcare, home repairs or other resources) for those affected.

3. Shop around.

If your car is on the fritz, it pays to shop around. Ask friends for reliable mechanic recommendations, and then call about deals, coupons and specials. Be sure the mechanic you pick gives you a quote before you agree to let them do any work. If their price is more than you can afford, ask for the bare-minimum fix that will get you back on the road safely until you can save for a bigger repair or a replacement car. If your vehicle is absolutely not drivable, consider carpooling or taking public transportation.

And if you need to replace an essential item (like a washer or an HVAC unit), start by browsing online. Look for coupon codes, compare prices, and see who offers free shipping. You’d be surprised how much money you can save with just a little bit of research.

4. Make extra money—fast!

Let’s be real: Sometimes, you just need more cash. Car repairs and new roofs aren’t cheap, after all. If you need more money, start by selling everything you don’t use anymore. Clean out your closet, attic or garage. Then hop on Craigslist or eBay to list your old bikes, iPads, DVDs, furniture, clothing and TVs to get some quick cash.

If you still need more money and have a little time, you may need to make some budget cuts. Can you cancel that gym membership? What about all those subscription services? Maybe you need to find ways to shrink that grocery budget. Even if it’s only in a couple of areas, those temporary cuts can add up to some big savings.

And then there’s just plain work! Look for ways to earn cash. Try delivering groceries or takeout, driving for Uber or Lyft, babysitting, walking dogs, or cleaning houses. There are also plenty of ways to boost your income without ever leaving your house—like freelancing, online teaching or bookkeeping. You can grow your financial safety net if you’re willing to get creative and make some sacrifices.

5. Build up your emergency fund again.

Once the dust settles and the storm has passed, it’s time to rebuild your emergency fund as soon as possible. If there’s one thing you can count on, it’s that there will be another emergency at some point. And when that happens, you’ll be thankful you had your emergency fund to help you weather the storm. So go ahead and focus on building that savings back up!

Get Peace of Mind

Wouldn’t it be nice to not have to worry about money when things go haywire? An emergency fund is more than just a financial buffer through hard times—it also gives you peace of mind!

Look, life happens. There’s always going to be something that tries to knock you down. But when you’ve got a fully funded emergency fund in place, you’ll be prepared instead of paranoid. You’ll be like the little pig who built his house out of brick. Having enough in savings lets you breathe and think through your options instead of panicking and making bad decisions.

If you’re ready to stop stressing and finally feel confident with your money, you can start today with Financial Peace University(FPU). It’s a nine-lesson video course you can watch from home that teaches you everything you need to know about saving for emergencies, paying off debt, and investing for your future. And great news: You can try FPU right now with a free 14-day trial of a Financial Peace! You’ll get all nine video lessons, plus tons of extra resources and tools to help you on your journey.

You can take control of your money and feel prepared for whatever life throws at you. Try FPU today! http://wordpress.com/refer-a-friend/RNlRO6gsz3AkwOnW0Wo3
Create your own website, free on WordPress.com.Create your own website.
Start free